AlphaBlog
Daily market commentary — what moved, why, and what to watch.
-
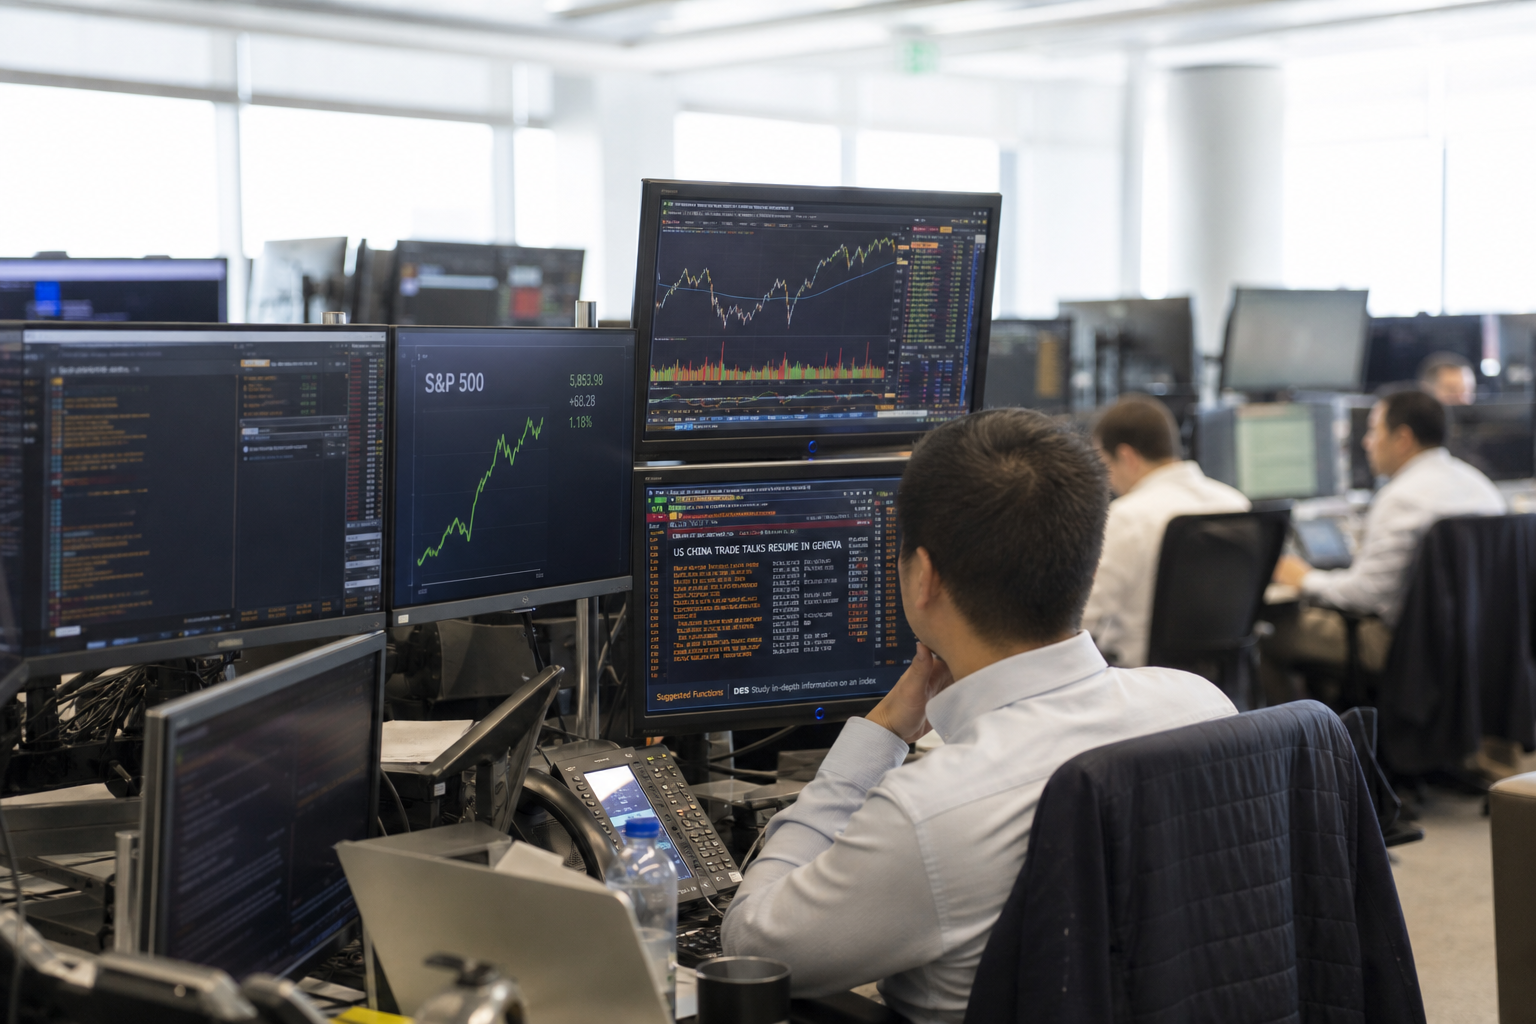
Markets Want Details, Not Summit Theater
Stocks are modestly higher as investors lean into the Trump-Xi meeting as a de-escalation setup. The real question is whether next week brings tariff and export-control changes that alter cash flows, not just headlines.
-
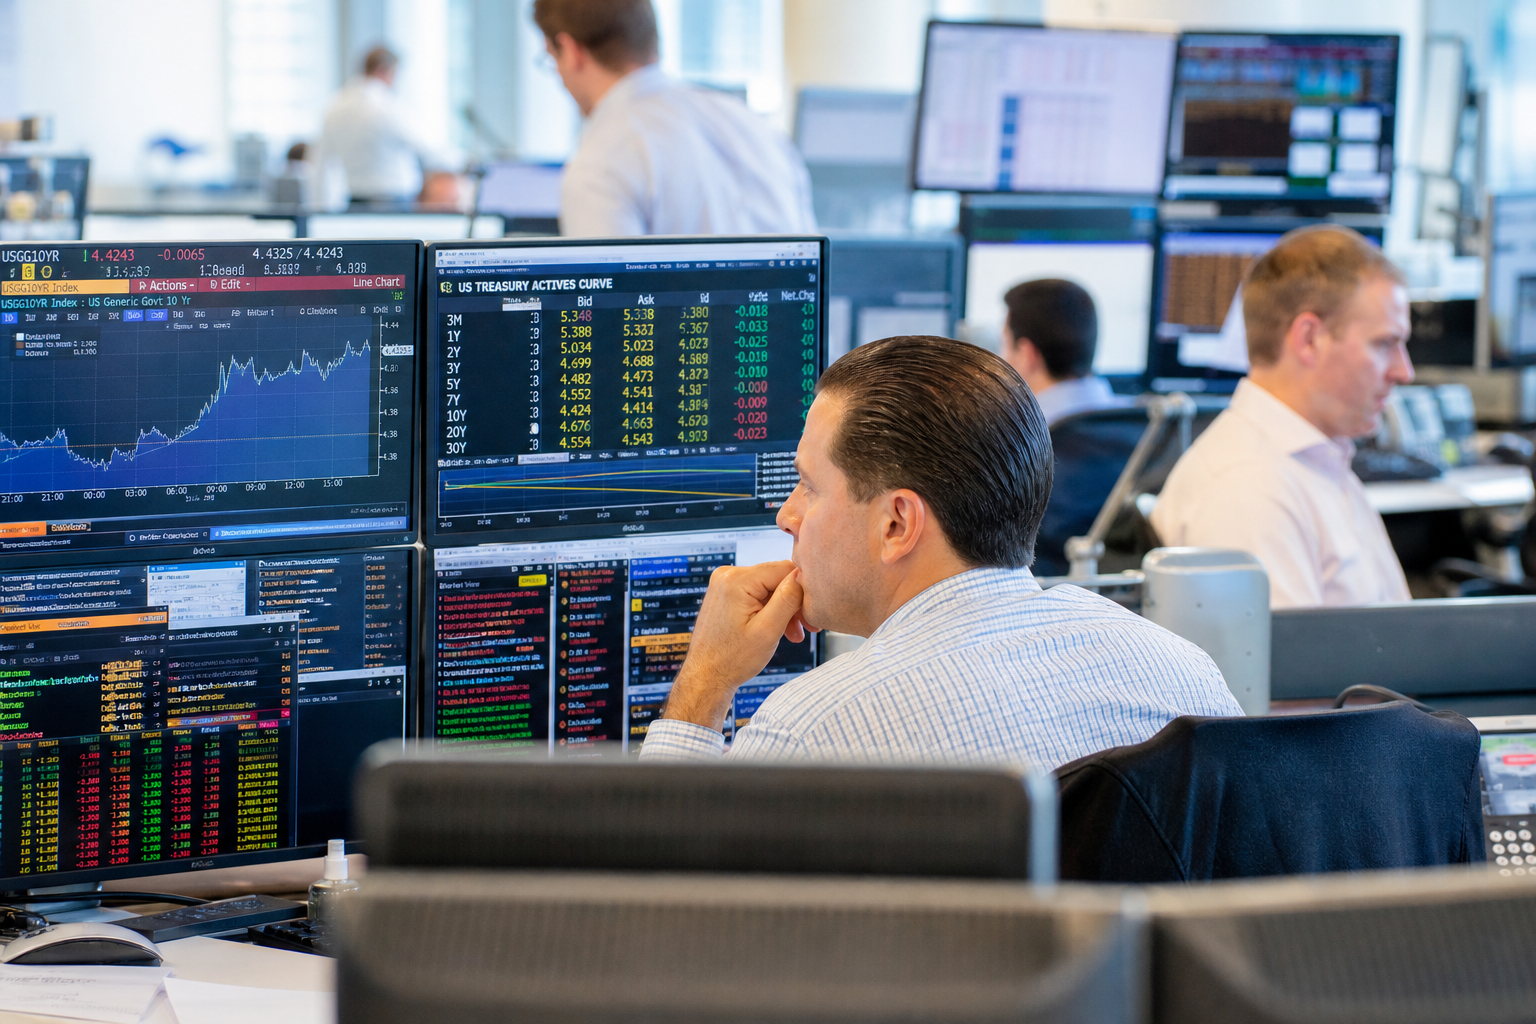
Treasury Yields Are the Real Market Boss
Stocks are slipping, but the louder message is coming from bonds. When long rates move to levels not seen in decades, equity valuations stop being a story about hope and start being a story about math.
-
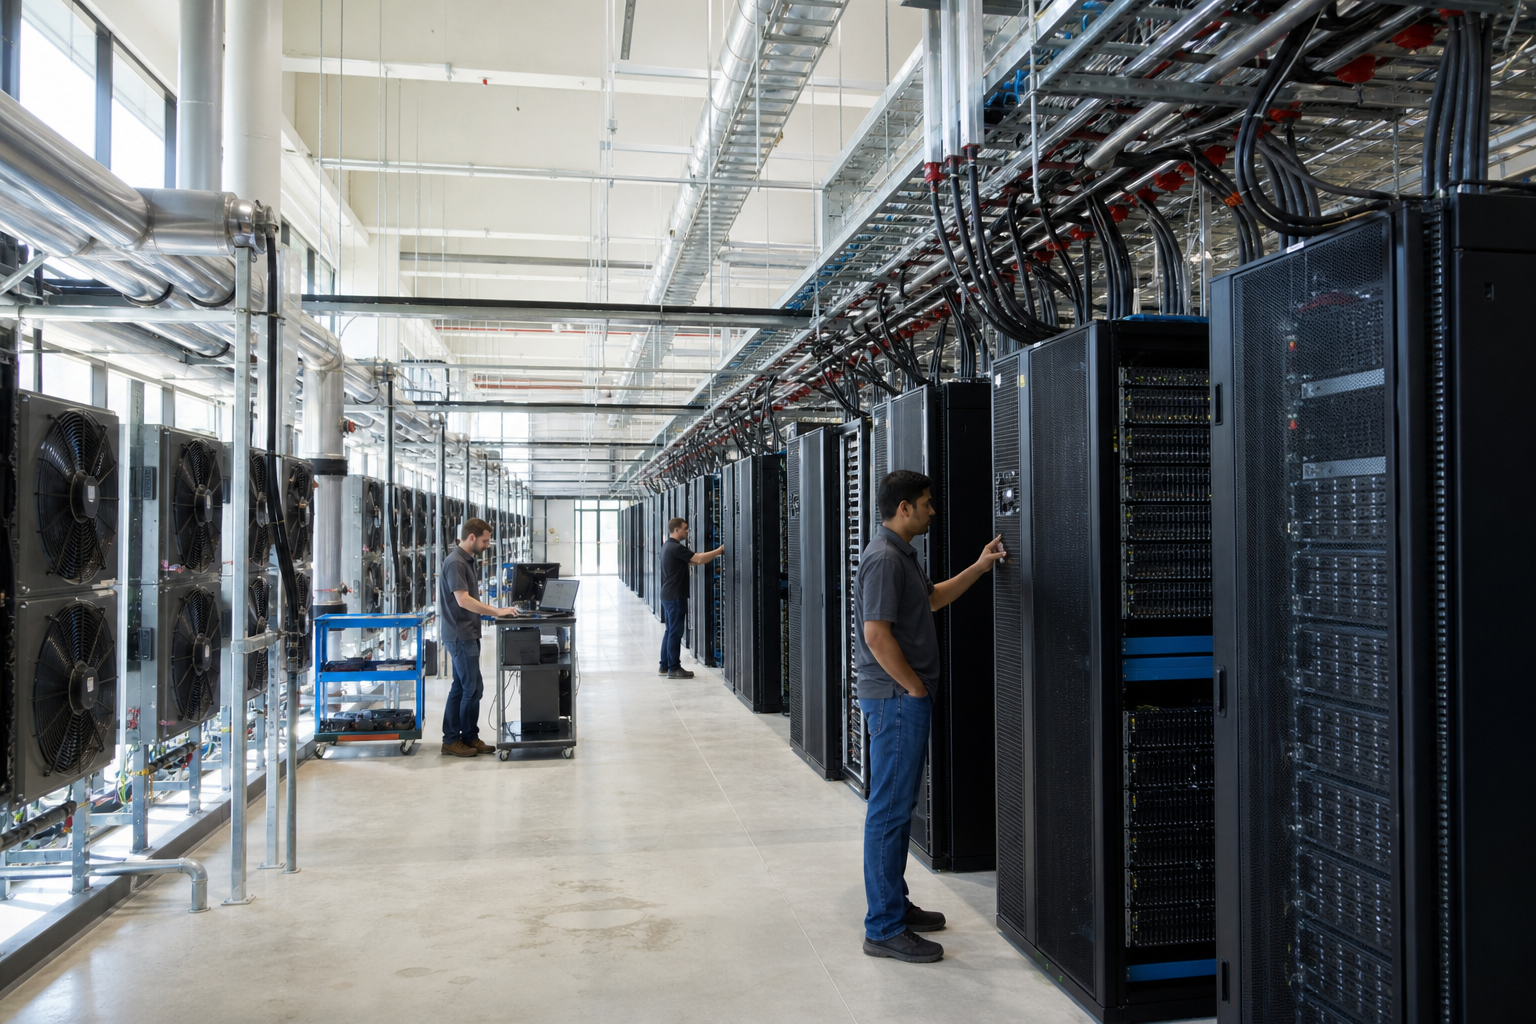
AI Capex Stops Looking Like a Story
Oracle and Nvidia just supplied what this market rarely gets in AI: concrete capacity, financing, and counterparties. That matters more than another round of vague enthusiasm.
-
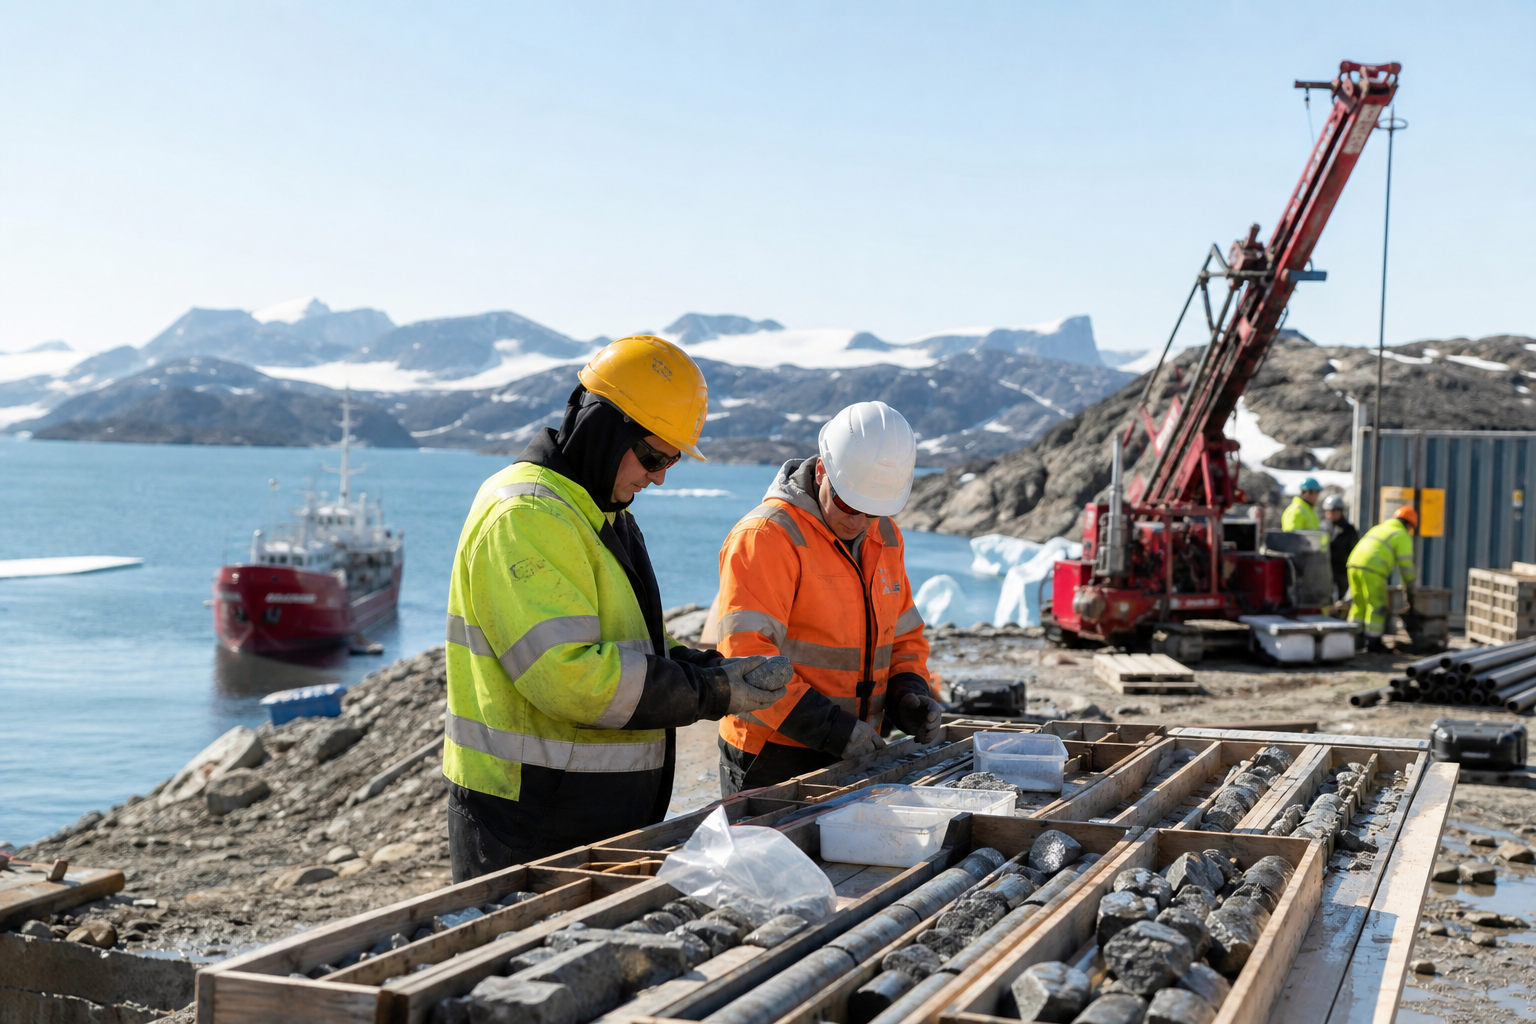
Greenland’s Security Deal Rekindles the Rare-Earth Trade
A new Greenland security agreement is doing more than stirring Arctic geopolitics. It is reminding investors that rare-earth supply chains are strategic assets, not just mining stories.
-
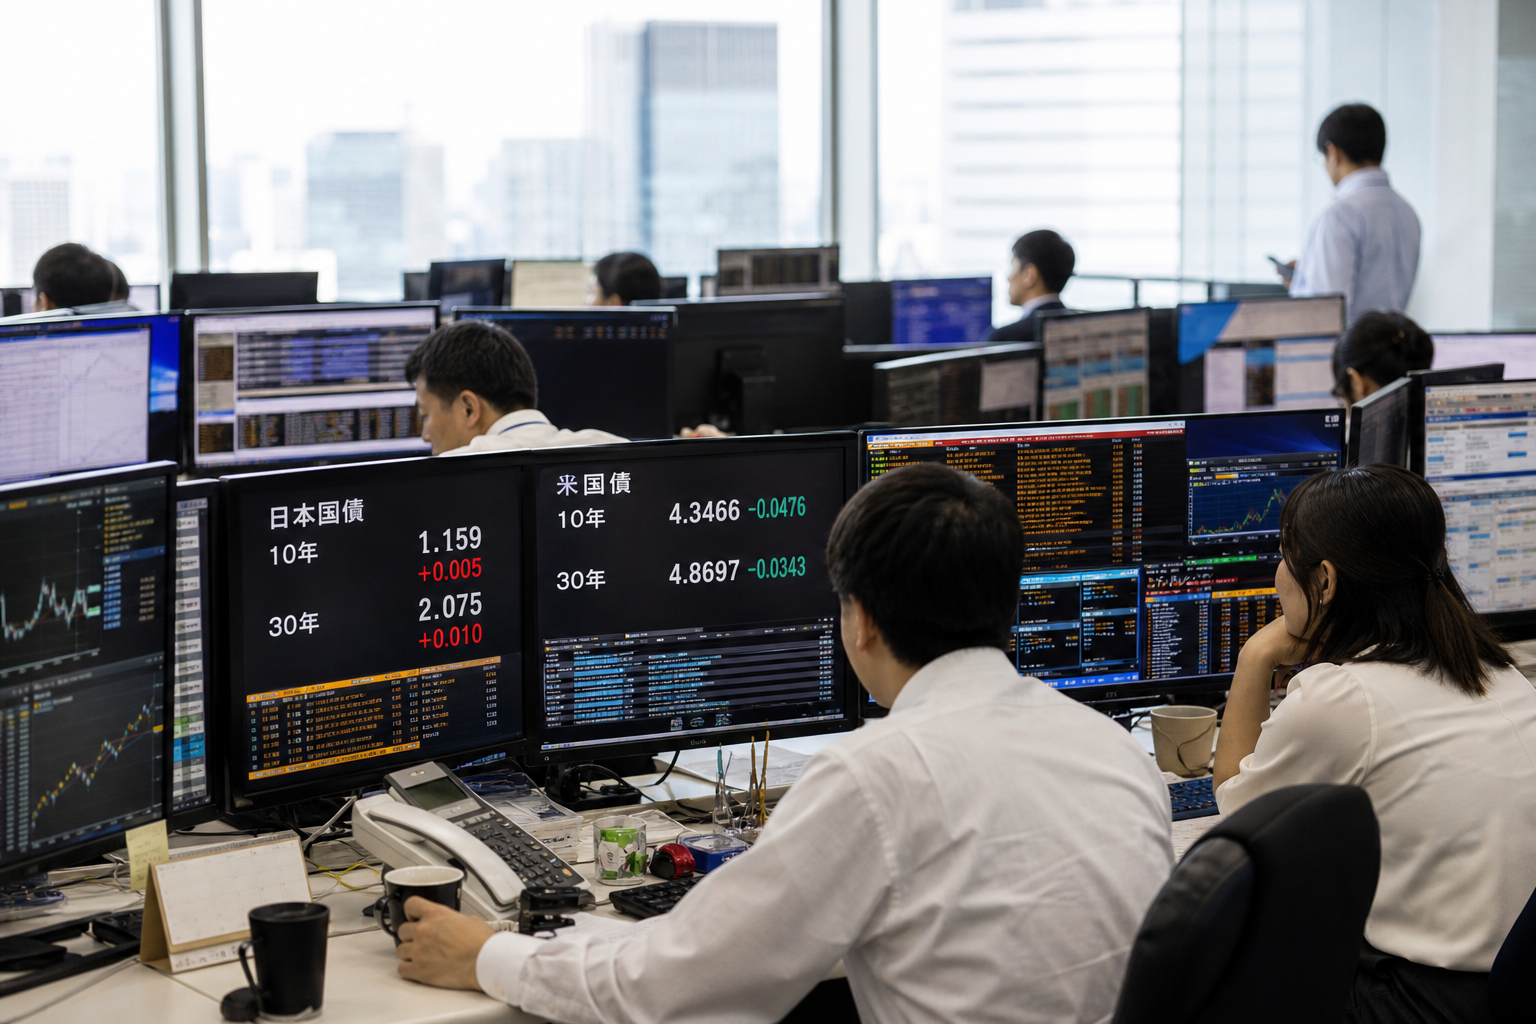
BOJ Tightens, and U.S. Small Caps Flinch
Japan just pushed rates to a 31-year high, and the first-order effect is simple: higher yields abroad make capital a little less cheap everywhere. U.S. indexes are only modestly lower so far today, but the pain is sharper in rate-sensitive corners.
-
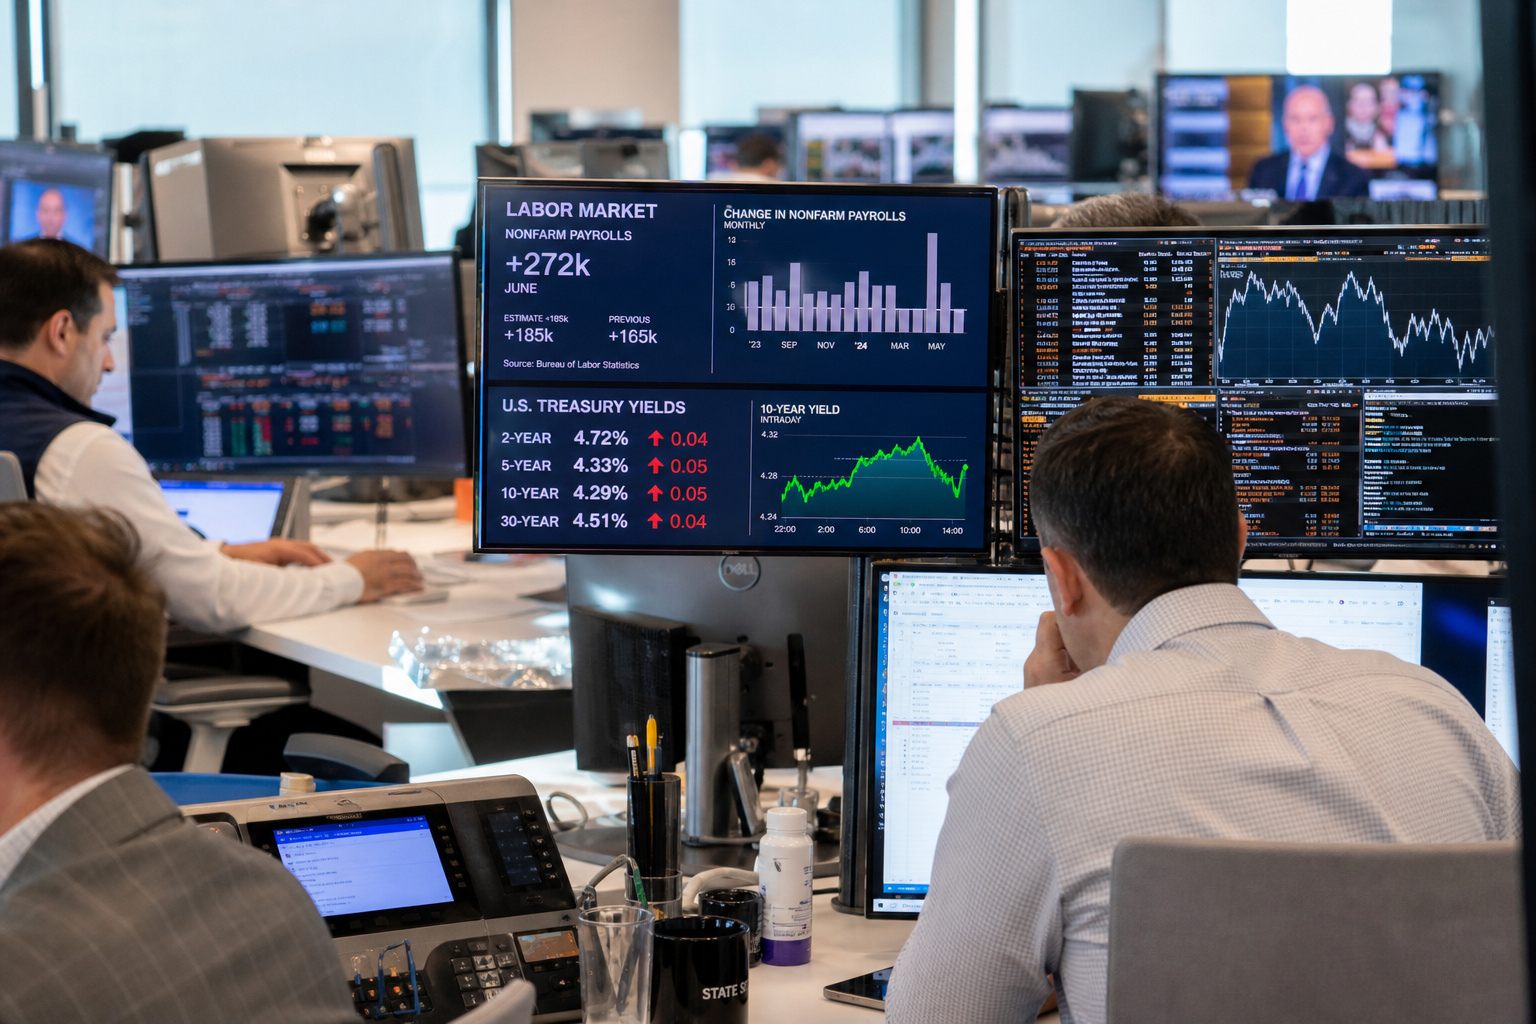
Strong Claims Data Keeps Easy-Money Dreams on Ice
Jobless claims fell again, and that matters more than another hour of index levitation. A labor market that refuses to crack gives the Fed less reason to rush, even as stocks cheer lower yields intraday.
-
A Split Tape Is Waiting on the Fed
Tech is leading, the Dow is lagging, and volatility is slipping. That looks less like a clean risk-on rally than a market marking time until the Federal Reserve speaks.
-
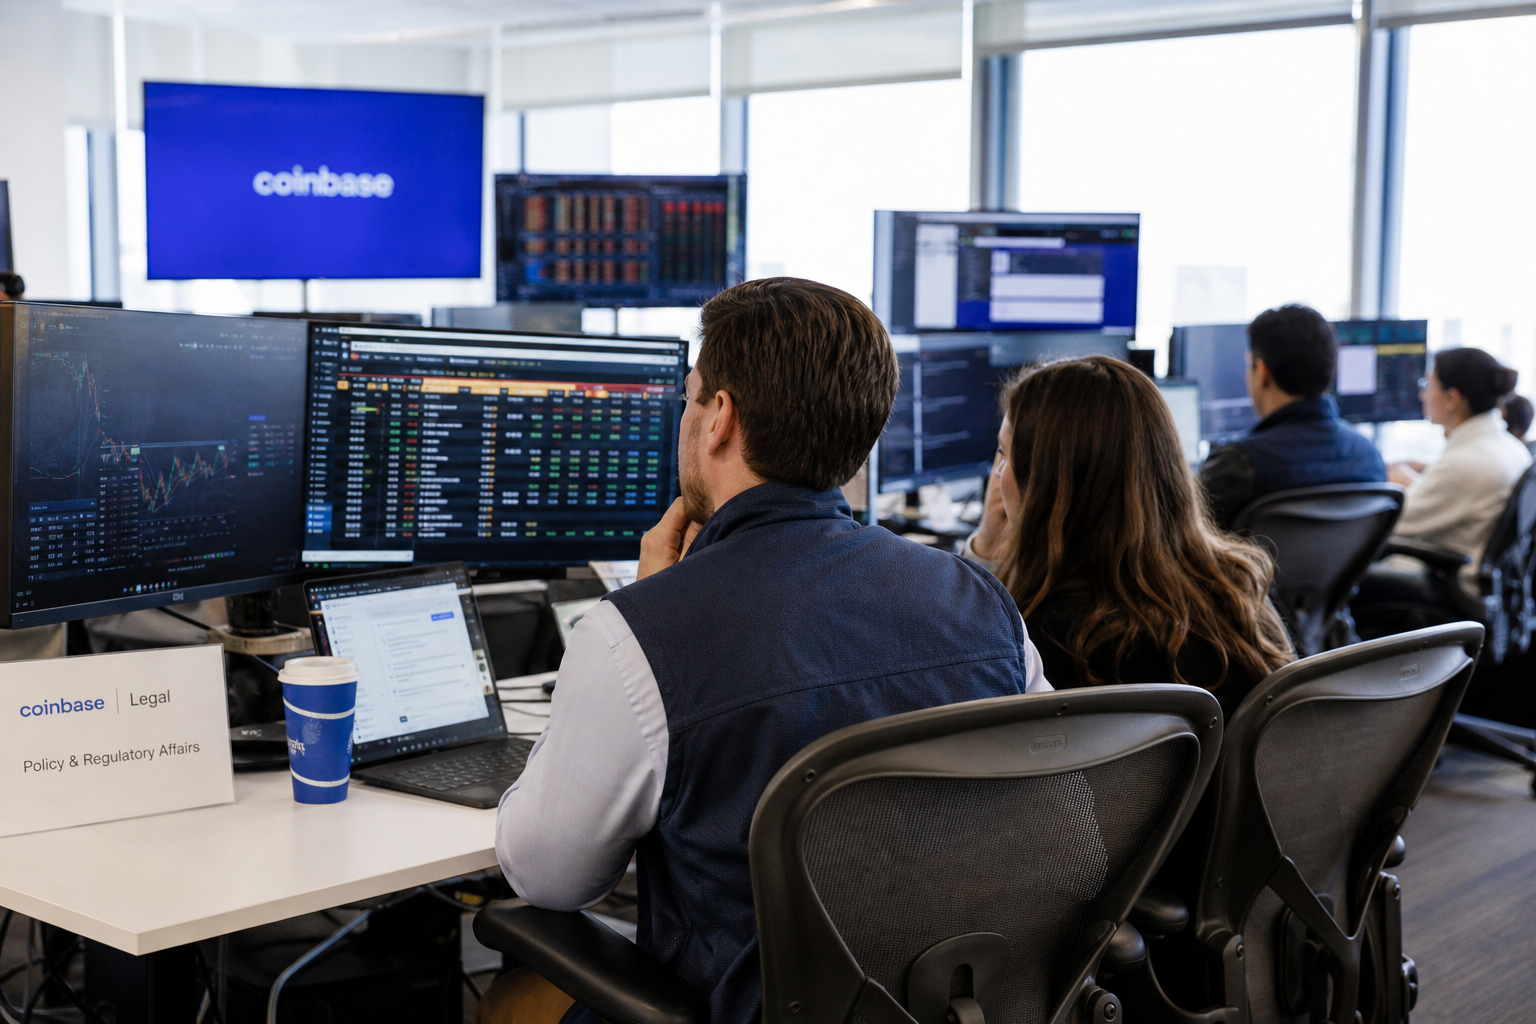
Crypto Stocks Flinch, Washington Matters More
Crypto-linked equities are softer ahead of a Senate vote on digital-asset legislation. The interesting question is not where coins trade this hour, but whether policy clarity starts separating real businesses from speculative luggage.
-
Defensive Tech Gets Its Day in the Sun
Cybersecurity is attracting capital while the broader tape sours on high-multiple AI infrastructure. When rates rise, oil jumps, and the equal-weight index outperforms, investors suddenly remember they like cash flows they can explain.
-

AI’s Next Bottleneck Isn’t Silicon
Washington is reheating AI regulation just as markets keep pricing frontier-model winners like pure infrastructure stories. That misses a simple point: policy can change economics faster than capex can.
-
Copper’s Drop Is Punishing the Miners
A near-5% intraday break in copper is giving investors a clean read on cyclicals: when the metal that touches housing, grids, and factories rolls over, miners get marked down first. This is less about drama than about margins, operating leverage, and how fast sentiment reprices a supposedly scarce asset.
-
Oil Hits Triple Digits, Stocks Flinch
Brent is back above $100, and that matters more than one red screen in the S&P 500. The real question is whether this is a brief fear bid or the start of a broader tax on margins, freight, and inflation expectations.
-
AI Buildout’s Real Winners Need More Than Chips
The fashionable trade is still AI compute. The sturdier question is what happens after everyone agrees to spend trillions on infrastructure: somebody must supply the power, cooling, and network plumbing.
-
Japan’s Rally Is the Real Macro Message
The cleanest signal into macro week isn’t in U.S. indices. It’s the widening gap between a surging Japan, a softer Hong Kong, and a hesitant U.S. tape as FX and rates do the talking.
-
Lululemon’s Reset Puts the Consumer on Trial
$LULU’s guidance cut matters beyond one apparel name. When a premium brand cites tariffs, macro uncertainty, weaker sales and lower margins in the same breath, the consumer debate stops being theoretical.
-
Oil’s Risk Premium Is Back in Charge
Crude is climbing on a fresh Gulf security shock, and the real story is not the commodity print itself. It’s the second-order effect: higher refined-product prices, stickier inflation optics, and a narrower margin of safety for rate-cut narratives.
-
California Utilities Learn Who Really Bears Fire Risk
California’s wildfire-liability fight is moving from politics into valuation. If investors can’t rely on a sturdier backstop, regulated utilities may deserve lower multiples and higher cost-of-capital assumptions.
-
Shein’s Wobbly Debut Meets a Tougher Market
Shein’s weak Hong Kong debut matters beyond one IPO. It is a live test of how much appetite investors still have for cross-border growth stories when rates are high, oil is rising, and hype no longer gets a free pass.
-
Warsh’s Jackson Hole Message Hits Long Duration
A hawkish Jackson Hole speech is doing what higher discount rates always do: pressing on duration-heavy equities while lifting the cost of wishful thinking. The real question is whether this is a one-day tremor or the start of a more stubborn repricing.
-
CrowdStrike Beat. The Stock Shrugged.
CrowdStrike delivered the kind of quarter most software CEOs would frame and hang on the wall. The problem is simpler and harsher: when a great business gets priced like an inevitability, good news stops being enough.


